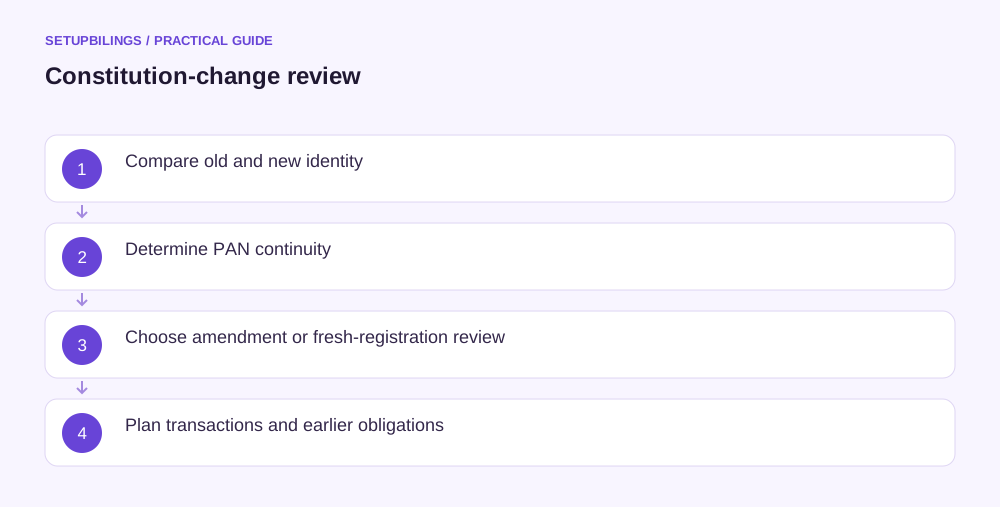
The decisive question is identity continuity
When a business changes constitution, determine whether the same legal person and PAN continue. Rule 19's registration framework requires fresh registration where a constitution change results in a change of PAN. An amendment to the old GST profile cannot convert one person's GSTIN into another person's tax identity.
This issue arises when a proprietorship becomes a partnership, a business is transferred to a company or another restructuring changes the applicant. The brand, premises and staff may remain familiar, but those commercial continuities do not settle the legal identity. Begin with the actual documents and PAN position, not the phrase used in a message announcing the change.
Separate different kinds of events
Some changes involve a continuing entity with updated constitution particulars and no new PAN. Others create or involve a different person. A partner's retirement, a company conversion, a business sale and a mere trade-name change should not be treated as the same event. Review the specific corporate, partnership or transfer records before selecting the GST action.
Make a before-and-after table with legal name, constitution, PAN, owners or stakeholders, business locations and intended start date. Mark which facts changed and which remain the same. If the new arrangement has not yet been legally completed, do not describe proposed future ownership as the current registered position.
The October 2026 GST Council release recommended changes to automatic processing of registration amendments. That process proposal does not turn a new PAN into an amendable field in an old GSTIN. Even if a faster amendment route is implemented, the underlying distinction between the same registrant and a different applicant remains essential.
Build the registration transition around a real date
Identify when the old person stops making supplies and the new person begins. Review contracts, stock transfer terms, customer orders and pending work. A chosen accounting cut-off should reflect the legal and commercial arrangement rather than create a period in which nobody is clearly responsible for invoices and liabilities.
Assess the new person's registration liability using the applicable provisions, including business-transfer or succession rules where relevant. Do not assume the new entity may trade without registration until its own receipts reach a fresh threshold. The statutory consequences of a transfer can differ from those of a completely new business starting independently.
Where fresh registration is required, prepare the new applicant's PAN, constitution evidence, premises rights and signatory authority. A lease or consent letter naming the old proprietor may need a genuine update or replacement to support the new firm's use. Simply uploading the old certificate cannot establish the new person's identity and right to occupy the premises.
Work through a transfer example
Illustratively, a sole proprietor transfers an operating repair business to a new company on 1 August. The company has a different PAN, while the shop name and ₹6 lakh of spare-parts stock continue. The parties should assess fresh company registration and the transfer consequences before issuing August invoices, rather than editing the proprietor's trade name to add “Private Limited.”
The transition file should identify who owns the stock at the cut-off, who collects old receivables, who fulfils pending customer work and which entity owes suppliers. A customer paying an old invoice into a new bank account does not automatically make the original supply belong to the new entity. Record the collection arrangement separately.
If the owner instead changes only the shop's brand while continuing as the same proprietor under the same PAN, that is a different review. A trade-name amendment may be relevant, but a fresh entity registration should not be invented solely to accommodate new signage. The documents must determine which scenario actually occurred.
Review credit, stock and liabilities separately
A fresh registration does not automatically move every tax credit balance, stock record or return obligation from the old person. Business transfers may involve specific credit-transfer provisions and forms, subject to conditions. Identify whether liabilities are transferred and whether the transaction structure qualifies before assuming credit can be carried across.
Prepare an inventory statement, open invoice list, credit-note position, advances, receivables, payables and tax ledger balances at the cut-off. Preserve the old and new GSTIN mapping. Obtain a transaction-specific assessment of the relevant forms and conditions where credit or liability transfer is involved, using the actual agreement and figures.
The old registration also needs a decision. It may continue for genuine ongoing supplies or require cancellation under the applicable process. Cancellation is not accomplished by abandoning the login. Review pending returns, tax liabilities, final return requirements and stock consequences as relevant to the taxpayer's facts.
Update operations before the first new invoice
Set up invoice series, bank records, supplier and customer masters, e-way bill arrangements where relevant and the new signatory's access. Ensure staff understand which entity may issue which document after the cut-off. A new logo pasted over an old invoice template can leave the wrong PAN-based GSTIN and legal name on every sale.
Reconcile the first reporting period for both persons separately. Check transactions straddling the transition, especially advances, returns and delayed collections. Retain links to the underlying original invoice so a later credit note or refund is handled by the appropriate person rather than whichever account is easiest to access.
A constitution-change review is complete when the identity decision and the operational records agree. That means the correct applicant holds the registration, supplies are attributed to the right person and the earlier account's obligations have a documented resolution.